Banks do not want to build a crypto desk from scratch. They want someone else to handle the wallets, the compliance and the settlement, to banking standards. That is the business Aquanow has built since 2018, and one of its co-founders says the biggest lesson was that good technology alone does not win the deal.
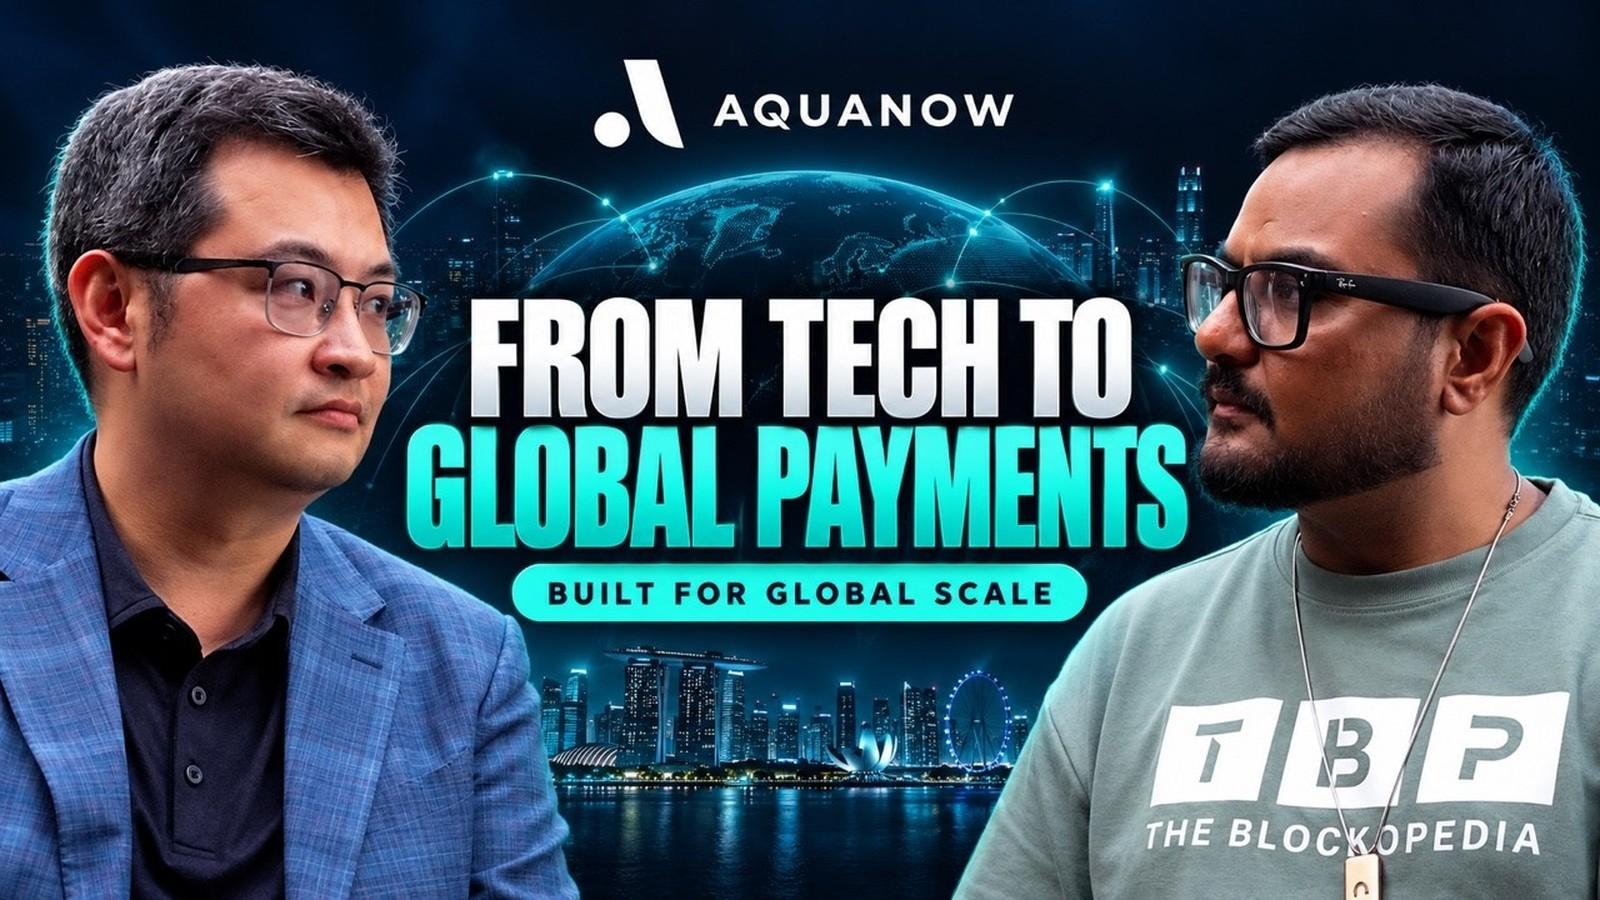
On the sidelines of Token2049 in Singapore, Mohammad Ahmad Khan, co-founder of The Blockopedia, sat down with Andy Leung, CTO and co-founder of Aquanow, for the TBP Podcast. Over about 18 minutes, they covered Andy’s move from bank capital markets into crypto, what Aquanow does for banks, its stablecoin partnership with Visa, its UAE licence, why crypto rules differ so much between countries and what keeps ordinary people from using crypto.
Key Takeaways
- Aquanow started in Canada in 2018 as B2B trading infrastructure, bringing a capital markets idea, liquidity aggregation, to crypto.
- It sits behind banks and other financial firms, handling wallets, compliance and other crypto complexity so clients mainly integrate its API.
- Andy says being only a technology provider was “not good enough”. Aquanow grew into a full-stack service covering onboarding, compliance, trading, settlement and custody.
- In its partnership with Visa, Aquanow uses stablecoins to offer better prices and faster cross-border settlement. Andy says bank-grade infrastructure and a strong compliance team made the case.
- He credits the UAE regulator’s work with industry for giving financial institutions confidence, and expects other countries to build their own frameworks over time.
- The biggest gap, in his view, is retail adoption. Wallets and user experience still create friction, while business adoption grows first.
From bank trading desks to crypto liquidity
Before Aquanow, Andy worked in bank capital markets, with exposure to equities, fixed income and FX. He and two fellow co-founders all came from that world. According to Aquanow’s website, Andy was previously a vice president of electronic trading at RBC Capital Markets, and he studied at the University of British Columbia and the University of Toronto.
At the banks, one problem they worked on was liquidity fragmentation. Put simply: how do you pull together liquidity from many different exchanges and offer one deep pool of it to banks and their clients? When the founders started Aquanow in Canada in 2018, they took the same idea to cryptocurrency. The market was new, and liquidity aggregation barely existed.
The plan was to build B2B trading infrastructure for financial institutions, but in Canada, Andy notes, financial institutions still have not offered crypto directly to their end clients. So in the first two or three years, Aquanow found other customers at home, including exchanges and robo-advisors. It built API solutions and integrated with these firms. “We were kind of the liquidity provider behind the scene,” he says.
After winning what he calls a pretty good market share in Canada, the company expanded abroad, first to Turkey, then the UAE, and now Asia. The UAE, he says, is one of its biggest and most focused markets today.
What Aquanow does for banks
Ahmad asks Andy to explain Aquanow as simply as possible. “Aquanow is a B2B trading infrastructure,” he answers. The product sits behind financial institutions and other business clients.
The idea is to hide the hard parts. Crypto brings operational and technical complexity, from wallets to compliance. When a client integrates with Aquanow, Andy says, Aquanow handles those pieces for it.
For a bank, that changes the staffing question. “They don’t have to have a crypto team,” he says, meaning a team whose skills sit outside the bank’s existing business. “What they need to do is just integrate with our API,” and then work with Aquanow on any customised workflows the bank requires.
Over time, the offer widened. In the UAE, Aquanow began providing what Andy calls an enterprise-level, full-stack crypto solution for banks, covering:
- onboarding
- compliance
- trading
- settlement
- custody
He describes this as the move from a pure liquidity provider to a full-stack enterprise solution, built for high availability and low latency. The newest product line is cross-border payments, which he says is quite different because it means licences in different jurisdictions, local payment partners and compliance in each market.
According to a November 2025 report by Electronic Payments International, Aquanow serves banks, neobanks, brokerages and payment companies, and employs more than 170 people across its global offices.
Why being a technology provider was not enough
One of the most candid points comes almost as an aside. When Aquanow started, Andy says, it was purely a technology provider. As it moved into new markets, the team learned that “only being a technology provider is not good enough” to serve a broader customer base.
So compliance, legal and regulatory expertise became part of the product. The goal, he says, is for customers to come to Aquanow “as a one-stop shop”, with a team that can answer their questions about entering new corridors. This matters most for payments, where each corridor, the route money takes between two countries, comes with its own rules.
The Visa partnership: stablecoins for faster cross-border settlement
Ahmad asks how Visa came to choose Aquanow for settlement in stablecoins. Andy places the deal in a wider trend: both Visa and Mastercard are moving into stablecoin solutions. He points out that Mastercard has acquired BVNK, a stablecoin infrastructure company. Mastercard’s quarterly filing with the US Securities and Exchange Commission confirms it completed that purchase on 3 August 2026, for $1.4 billion in cash plus up to $300 million in performance-linked payments.
Aquanow brings trading to the Visa work, Andy says, plus on-ramp and off-ramp, the steps that move money between regular currency and crypto. It also adds compliance and regulatory expertise to help Visa work through different corridors. He calls it a joint effort to serve Visa’s customers, using stablecoins to give them a better price and better speed on cross-border payment and settlement.
Visa announced the partnership in November 2025. According to Visa’s announcement, it expands Visa’s stablecoin settlement capabilities across Central and Eastern Europe, the Middle East and Africa (CEMEA). Visa’s network of card issuers and acquirers in the region can settle transactions using approved stablecoins such as USDC.
What convinced Visa? Andy points to track record. Aquanow’s trading infrastructure already met banking standards, which he says proved it could serve financial institutions, and years of work with banking clients built its reputation. For Visa, he says, that answered one checkpoint: does the technology meet the level they would expect?
The second checkpoint was that Aquanow is more than a technology vendor. Andy credits the company’s compliance and regulatory team with helping to explore how to open different corridors.
Getting licensed in the UAE, alongside the regulator
Ahmad notes that many companies chase licences, sometimes spending huge sums, and come away with nothing. He asks how Aquanow got its licence in the UAE.
When the UAE started drafting its virtual assets regulatory framework, Andy says, Aquanow was there and worked alongside the regulator. Seeing officials spend time talking to the industry gave the team confidence. “Without the proper regulatory framework, it is hard for financial institution to get into that space,” he says.
Aquanow was one of the early firms to get a brokerage licence, he says, and among the first few to talk to banks once it had it. Serving financial institutions had been the company’s goal from the start. Dubai’s Virtual Assets Regulatory Authority (VARA) gave Aquanow full operational approval in July 2024, according to the company’s announcement at the time. Its licence covers broker-dealer, lending and borrowing, and management and investment services.
Andy also welcomes competition. As the framework matures, more participants will come in, which he calls healthy for the market and a sign of confidence in the rules.
Why many countries are still unclear on crypto
Ahmad puts a common frustration to him. A founder from Canada, Singapore or India may want to build at home, but unclear rules push them to move to the UAE. What does Andy make of that?
He sees it as a matter of time. He points to the United States, which now has the GENIUS Act, a federal law for payment stablecoins signed in July 2025, and is working on wider regulation. In his view, there is no doubt the industry will mature, with more adoption and stronger frameworks across more countries. He names Turkey and Southeast Asia as places where a lot of work is in progress.
Now that some frameworks exist, Andy expects other jurisdictions to study them and set up their own, and more countries to have their own stablecoins. Regulators have a lot to think about, he says, but more institutional and business adoption is coming. “It is just a matter of time,” he says, for regulation to mature and for adoption to spread to more countries.
What still stands in the way of everyday use
Asked about a myth the industry still holds, Andy turns to mass adoption. Business adoption is rising, he says, because the infrastructure has become more mature, more robust and more reliable. That is the starting point.
The open question is retail. Bitcoin arrived in 2009, so why has everyday adoption not followed? Andy asks whether the cause is the user experience, the wallet, and “certain complexity in the crypto that’s still creating friction” for normal people.
His view is that adoption will come down from the business side first, built on real use cases that save time, save money and deliver faster. The next step is to bring retail users in as well, which he says would be good for the whole ecosystem.
He also sees growth in tokenization. Alongside stablecoins, he says, the market needs more investable products on-chain, and that work is under way.
What’s next for Aquanow: start with the client’s pain point
On future plans, Andy calls payments an interesting domain. With stablecoin payments covering many corridors, the company has to decide which markets to prioritise and enter first.
His method is to listen to clients. What do they need? Where are they from? Where is the pain point, and how does Aquanow’s solution fit it? The technology will keep improving, he says, but the use case comes from what clients need, and serving them well is the key.
Ahmad picks up on this at the end, saying many companies in the space miss this focus on customer feedback.
Advice for anyone building in this space
Andy’s first piece of advice is about pace. “The crypto world is still moving really fast,” he says. Anyone who wants to get into the industry should “pay attention to what’s happening in the regulatory side” and to developments in different jurisdictions, because regulation is what allows the industry to grow.
Technology keeps changing too. In payments, he lists orchestration, integration and partnerships as big questions, and some of these are not blockchain problems at all. The interesting work is bringing different pieces together and connecting them to a blockchain solution.
His last suggestion is for people outside crypto trading and payments: think about how blockchain technology could be used in your own industry. That, he says, is one way to help the whole sector grow.
Final thoughts
The interview offers a practical picture of how crypto reaches the mainstream: through banks and payment networks first, with the complexity hidden behind an API. Andy’s lesson is that this takes more than code. Aquanow’s path from a Canadian liquidity provider to a licensed, full-stack partner for banks and Visa rests as much on compliance and regulatory work as on technology.
Some of what he describes is on the public record: the Visa partnership, the VARA licence and Mastercard’s purchase of BVNK. Other points are forecasts, such as more countries building clear frameworks, more national stablecoins and retail adoption following business use. Treat those as one builder’s view of where the market is heading.
Watch the full conversation on the TBP Podcast YouTube channel.
Frequently Asked Questions
Q: What is Aquanow?
Aquanow is a B2B digital asset infrastructure company founded in Canada in 2018. It works behind banks and other financial institutions, handling crypto trading, onboarding, compliance, settlement and custody through an API.
Q: Who is Andy Leung?
Andy Leung is the CTO and co-founder of Aquanow. He came from bank capital markets, with experience in equities, fixed income and FX, and leads the company’s technology and platform development.
Q: What is the Visa and Aquanow partnership?
Announced in November 2025, the partnership expands Visa’s stablecoin settlement in Central and Eastern Europe, the Middle East and Africa. It lets Visa’s issuers and acquirers settle transactions in approved stablecoins such as USDC. Andy says Aquanow contributes trading, on-ramp and off-ramp services, and compliance expertise.
Q: How do stablecoin cross-border payments help banks?
Andy says stablecoins can give customers a better price and faster cross-border settlement. Banks using a provider like Aquanow do not need their own crypto team; they integrate an API while the provider handles wallets and compliance.
Q: Does Aquanow hold a licence in the UAE?
Yes. Dubai’s Virtual Assets Regulatory Authority (VARA) gave Aquanow full operational approval in July 2024, covering broker-dealer, lending and borrowing, and management and investment services. Andy says the company worked alongside the regulator while the framework was being drafted.
Q: What is holding back everyday crypto adoption?
Andy says business adoption is growing as infrastructure matures, but retail users still face friction from user experience, wallets and crypto complexity. He expects businesses to lead, with retail following. This is an industry view, not investment advice – digital assets, including stablecoins, carry risks.